The Changing Gifting Basket In India-A
Category
FMCG / GIFTING
Context
Understanding how the mix of gifting products entering India-A households is changing across categories, occasions and household pools.
Year
MAT June 2026
Key Insight
As gifting broadens beyond traditional formats, India-A’s basket is becoming less chocolate-led, with Fragrance and Dry Fruits & Nuts gaining a stronger role across households and occasions.
Gifting Goes Beyond the Traditional Gift Pack
Gifting isn’t limited to one category or format. Across FMCG, many products are designed and positioned specifically for gifting. Together, these products form a sizable gifting universe across India-A, spanning five broad spaces:
Chocolate & Sweet Snacking, Fragrance, Dry Fruits, Nuts & Health-led Snacking, Traditional Food Gifting, and Personal Care & Grooming. For this analysis, gifting products are identified through front-of-pack gifting cues such as Gift Set, Gift Pack, Festive, Gift Box, Celebration and Diwali.
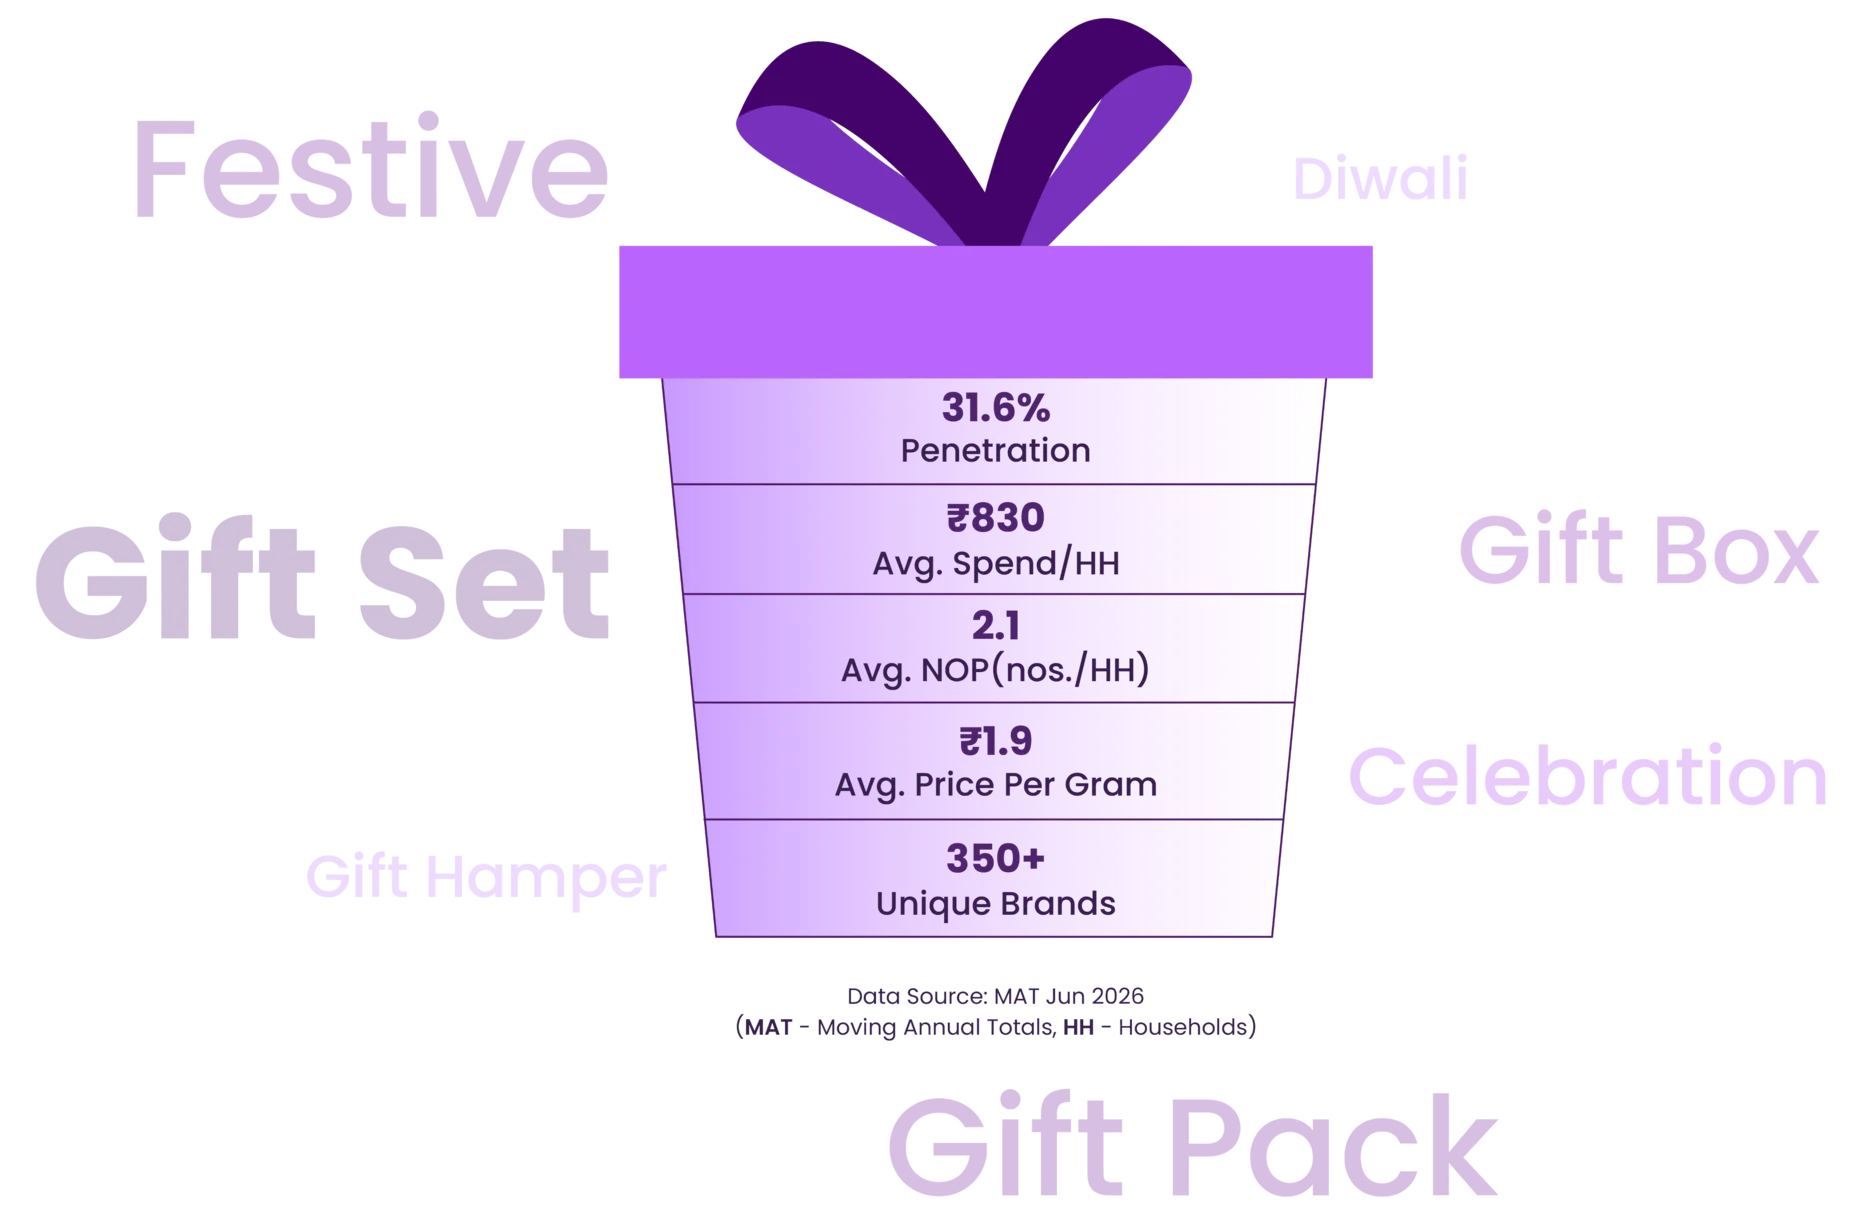
Gifting products enter nearly 1 in 3 India-A households, with an average value of ₹830 per household across 350+ brands and 850+ SKUs. But the mix of gifting products entering these households is changing.
Gifting Holds Value Even as Household Reach Softens
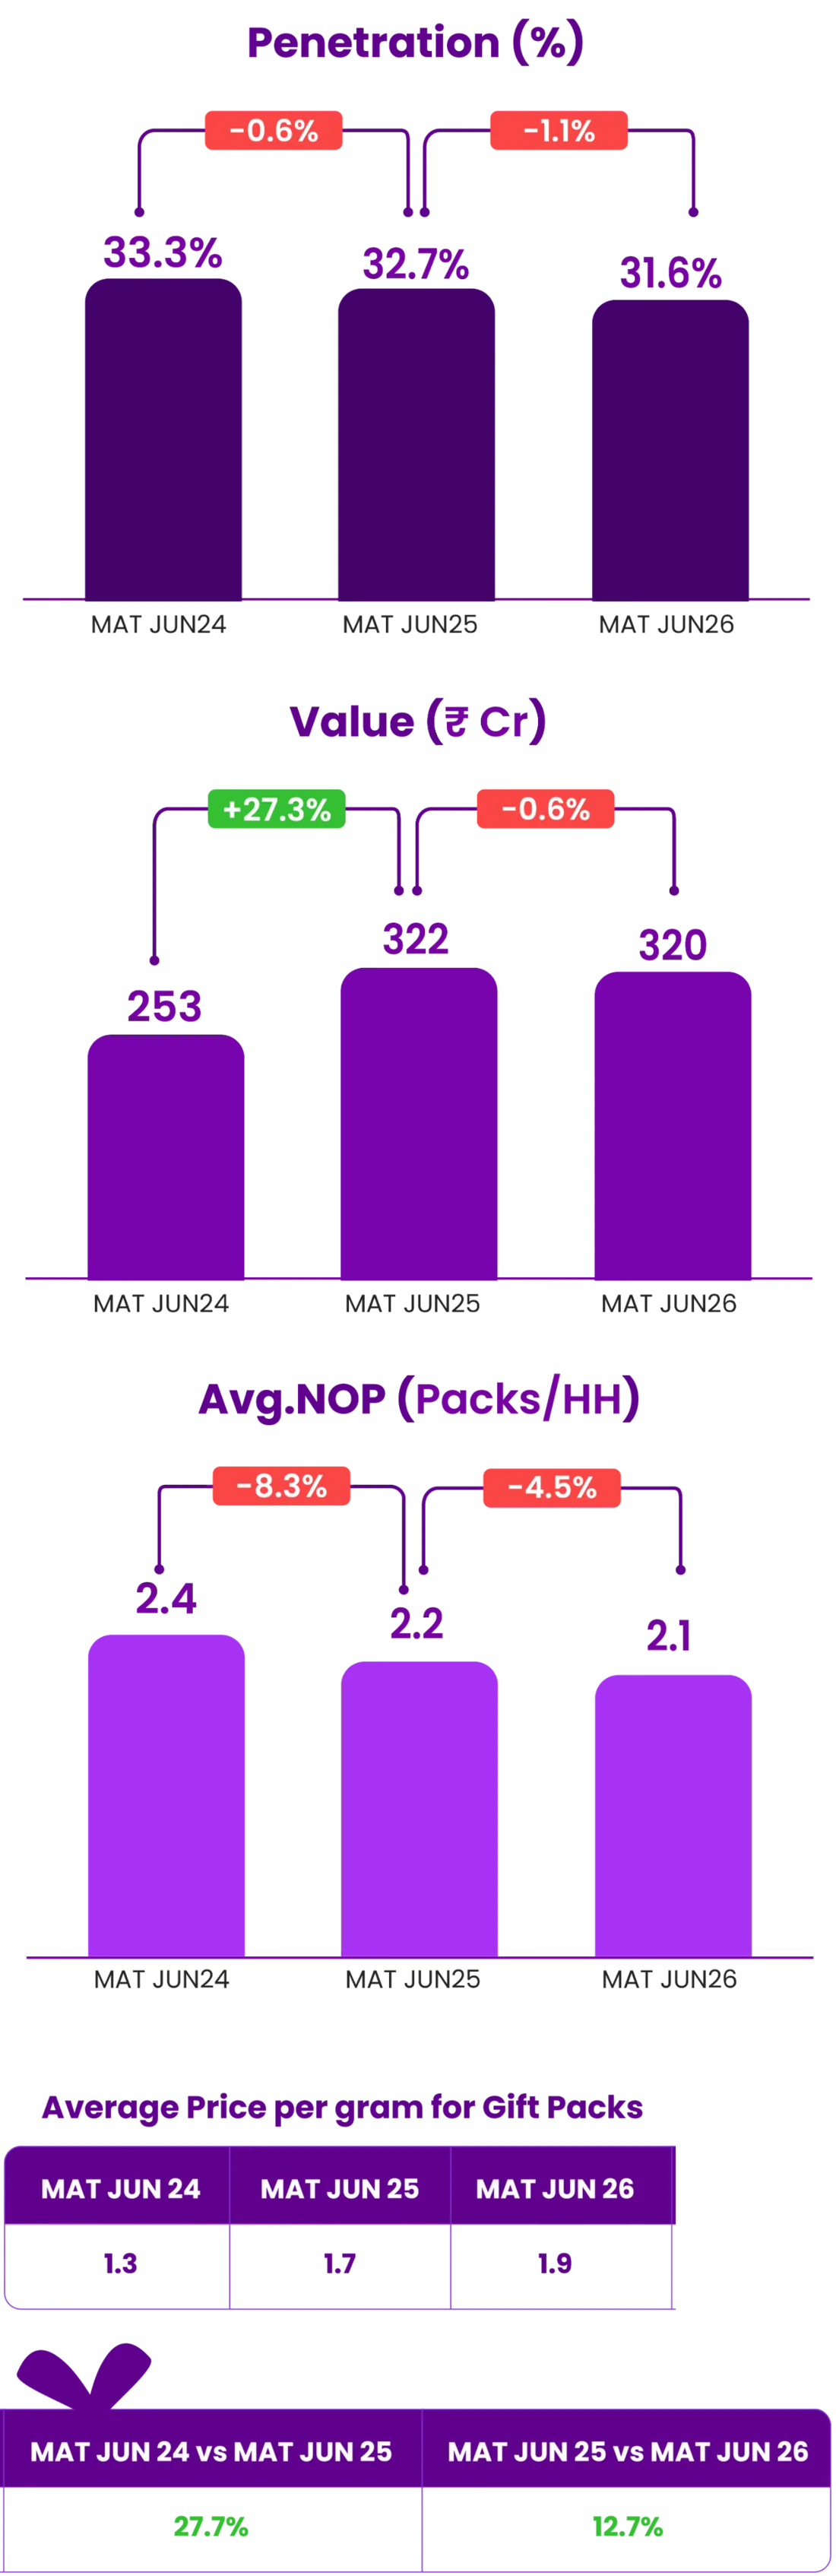
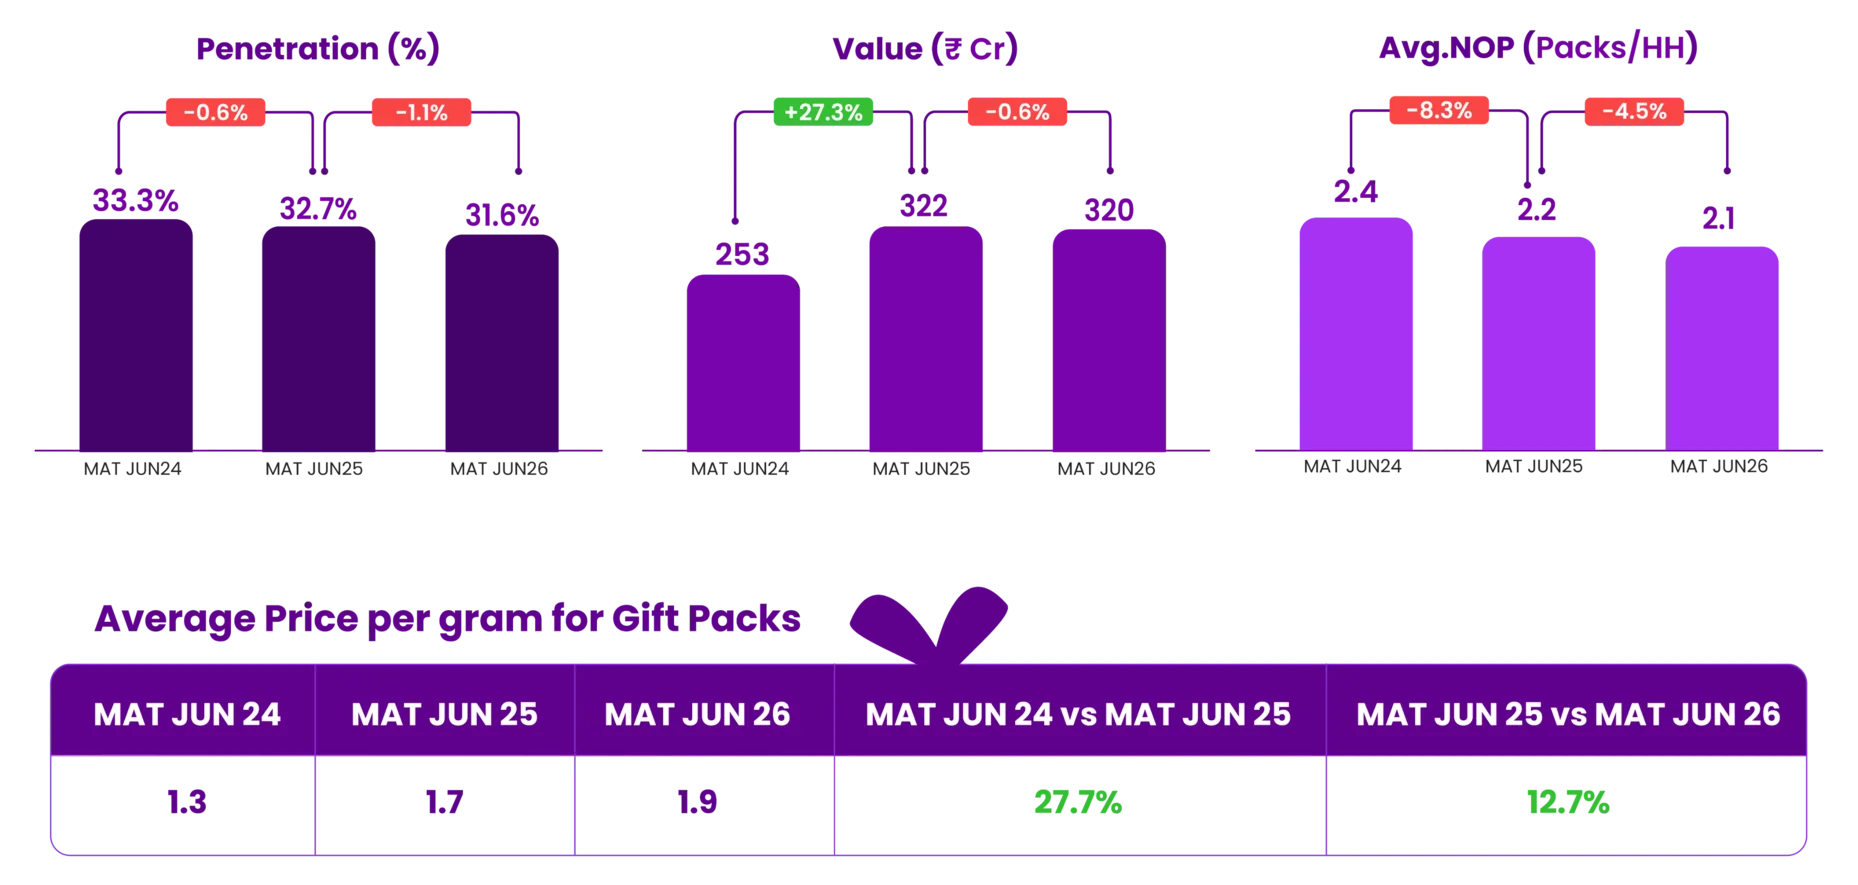
Gifting value has stayed broadly stable in MAT Jun’26, even as household reach declined and the number of packs per household softened. At the same time, average price per gram increased. So while overall gifting value has held steady, the mix within it is starting to look different.
The Gifting Basket Is Becoming More Diverse
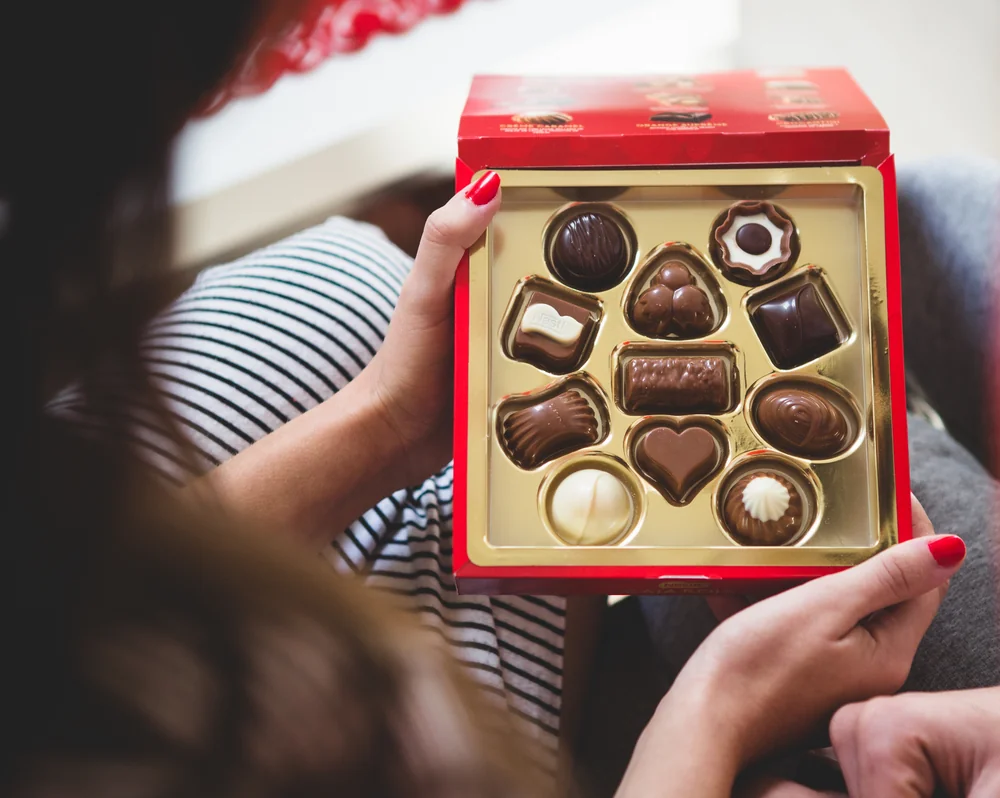
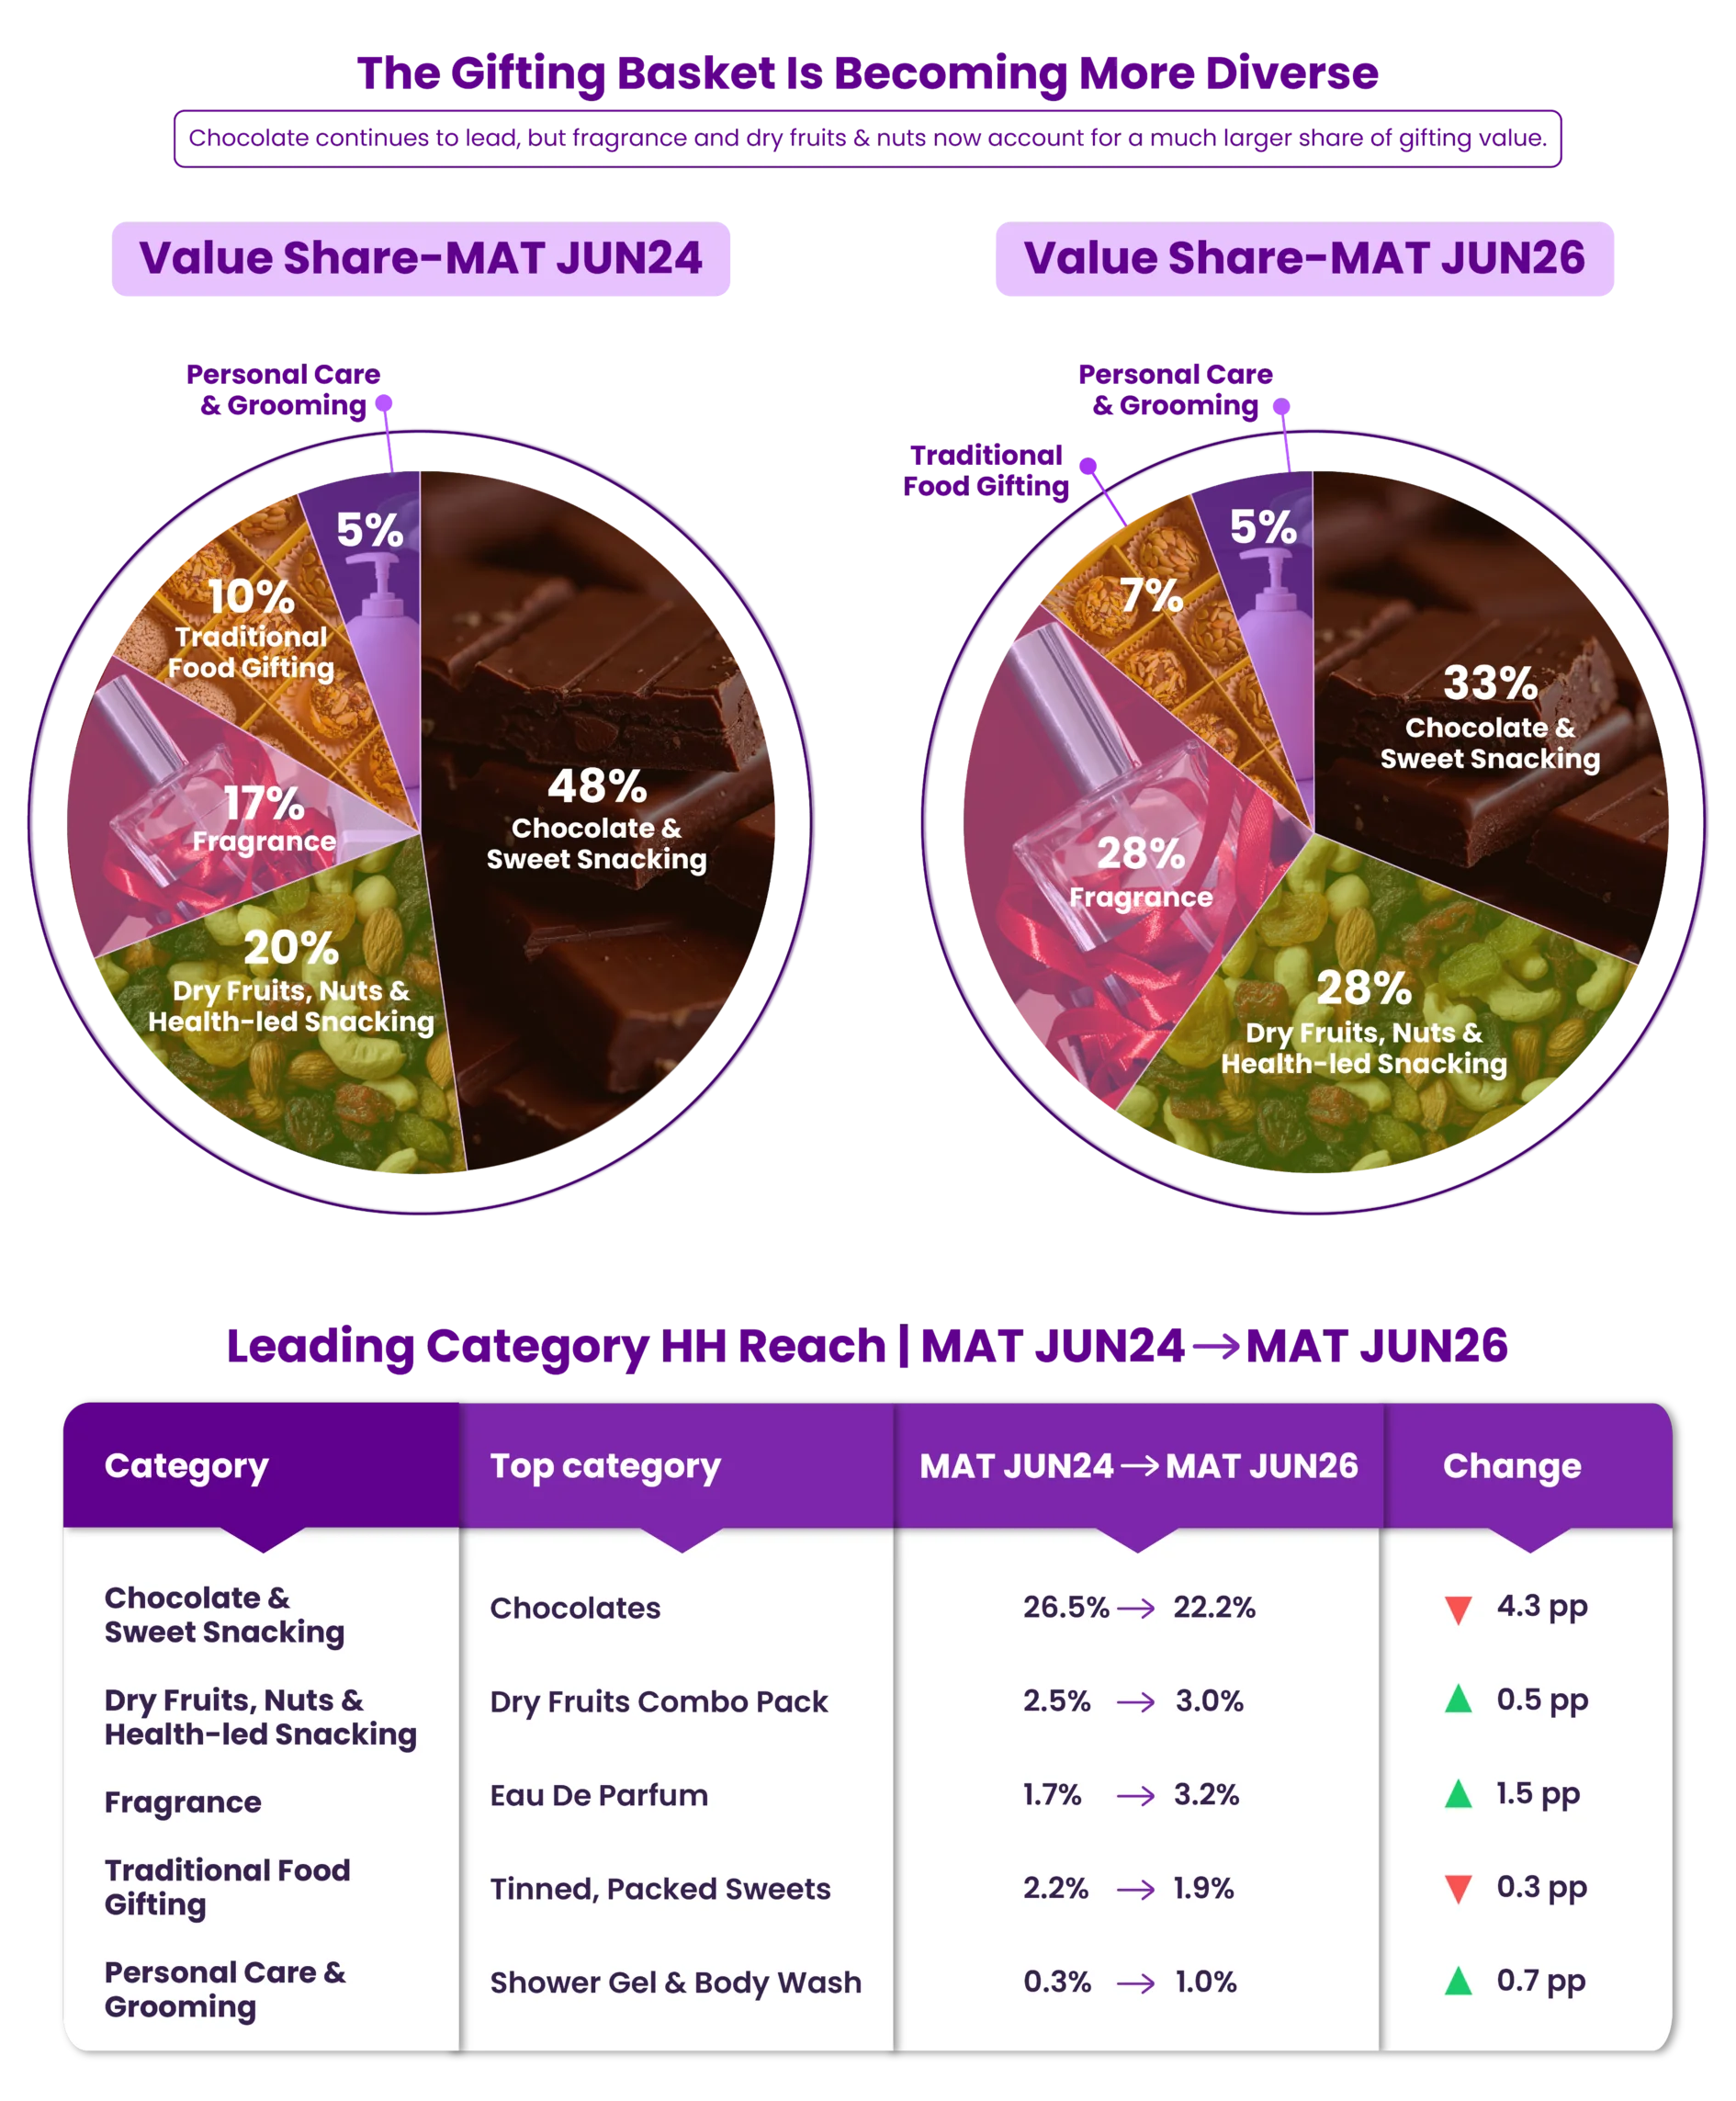
Chocolate & Sweet Snacking remains the largest of the five gifting spaces, but it now accounts for a smaller share of gifting value than two years ago. Over the same period, Fragrance and Dry Fruits, Nuts & Health-led Snacking have become much larger parts of the gifting basket, narrowing the gap with Chocolate.
Even the Gifting Peak Is Changing
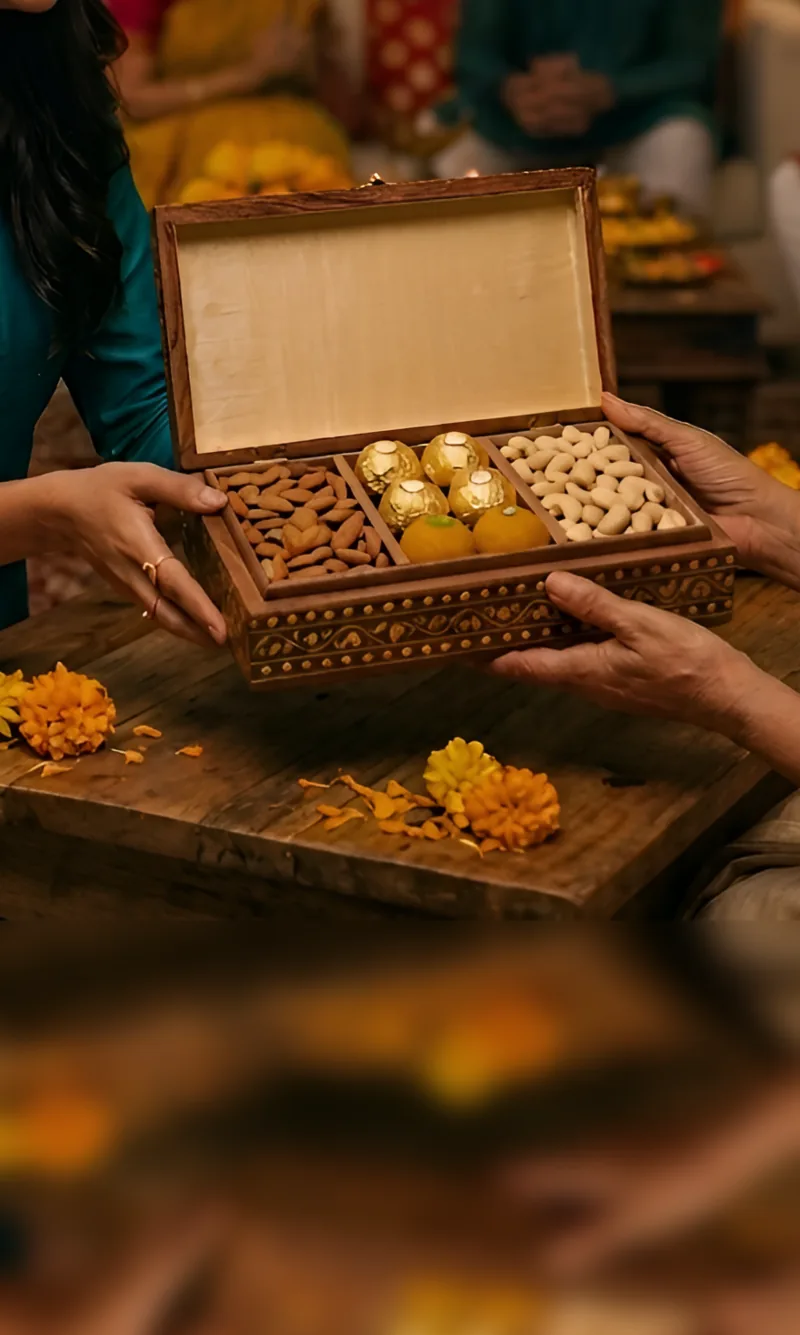
Q4 (October-December) remains the strongest gifting period, but the mix within that peak is shifting. Dry Fruits & Nuts has grown into a much larger part of Q4 gifting value and overtook Chocolate in the latest Q4.
Quarterly Value Trend by Gifting Space: Q1’22 - Q2’26
Value (Rs. Crore)
- Chocolate & Sweet Snacking
- Dry Fruits, Nuts & Health-led Snacking
- Fragrance
- Traditional Food Gifting
- Personal Care & Grooming
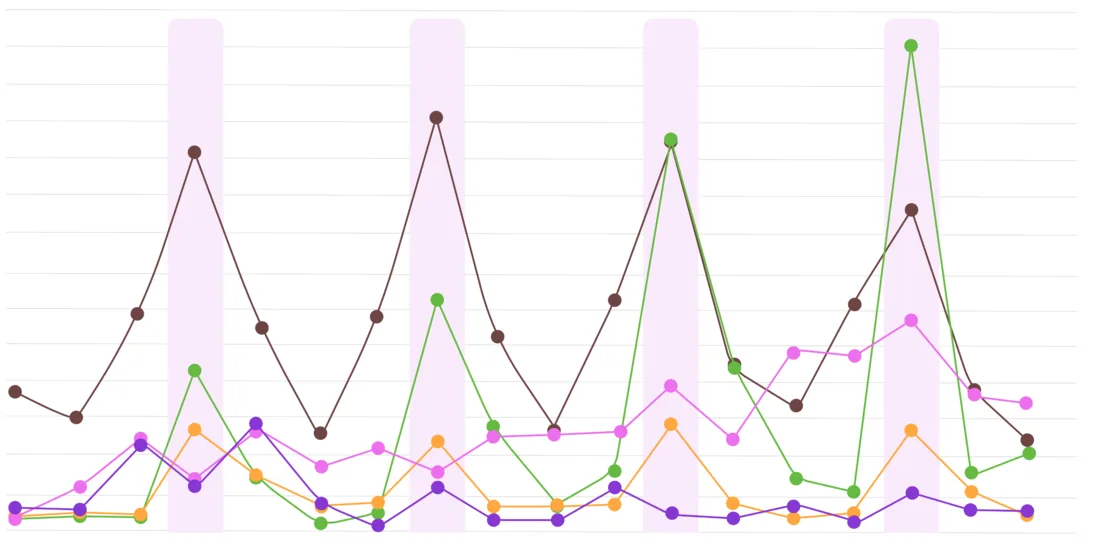
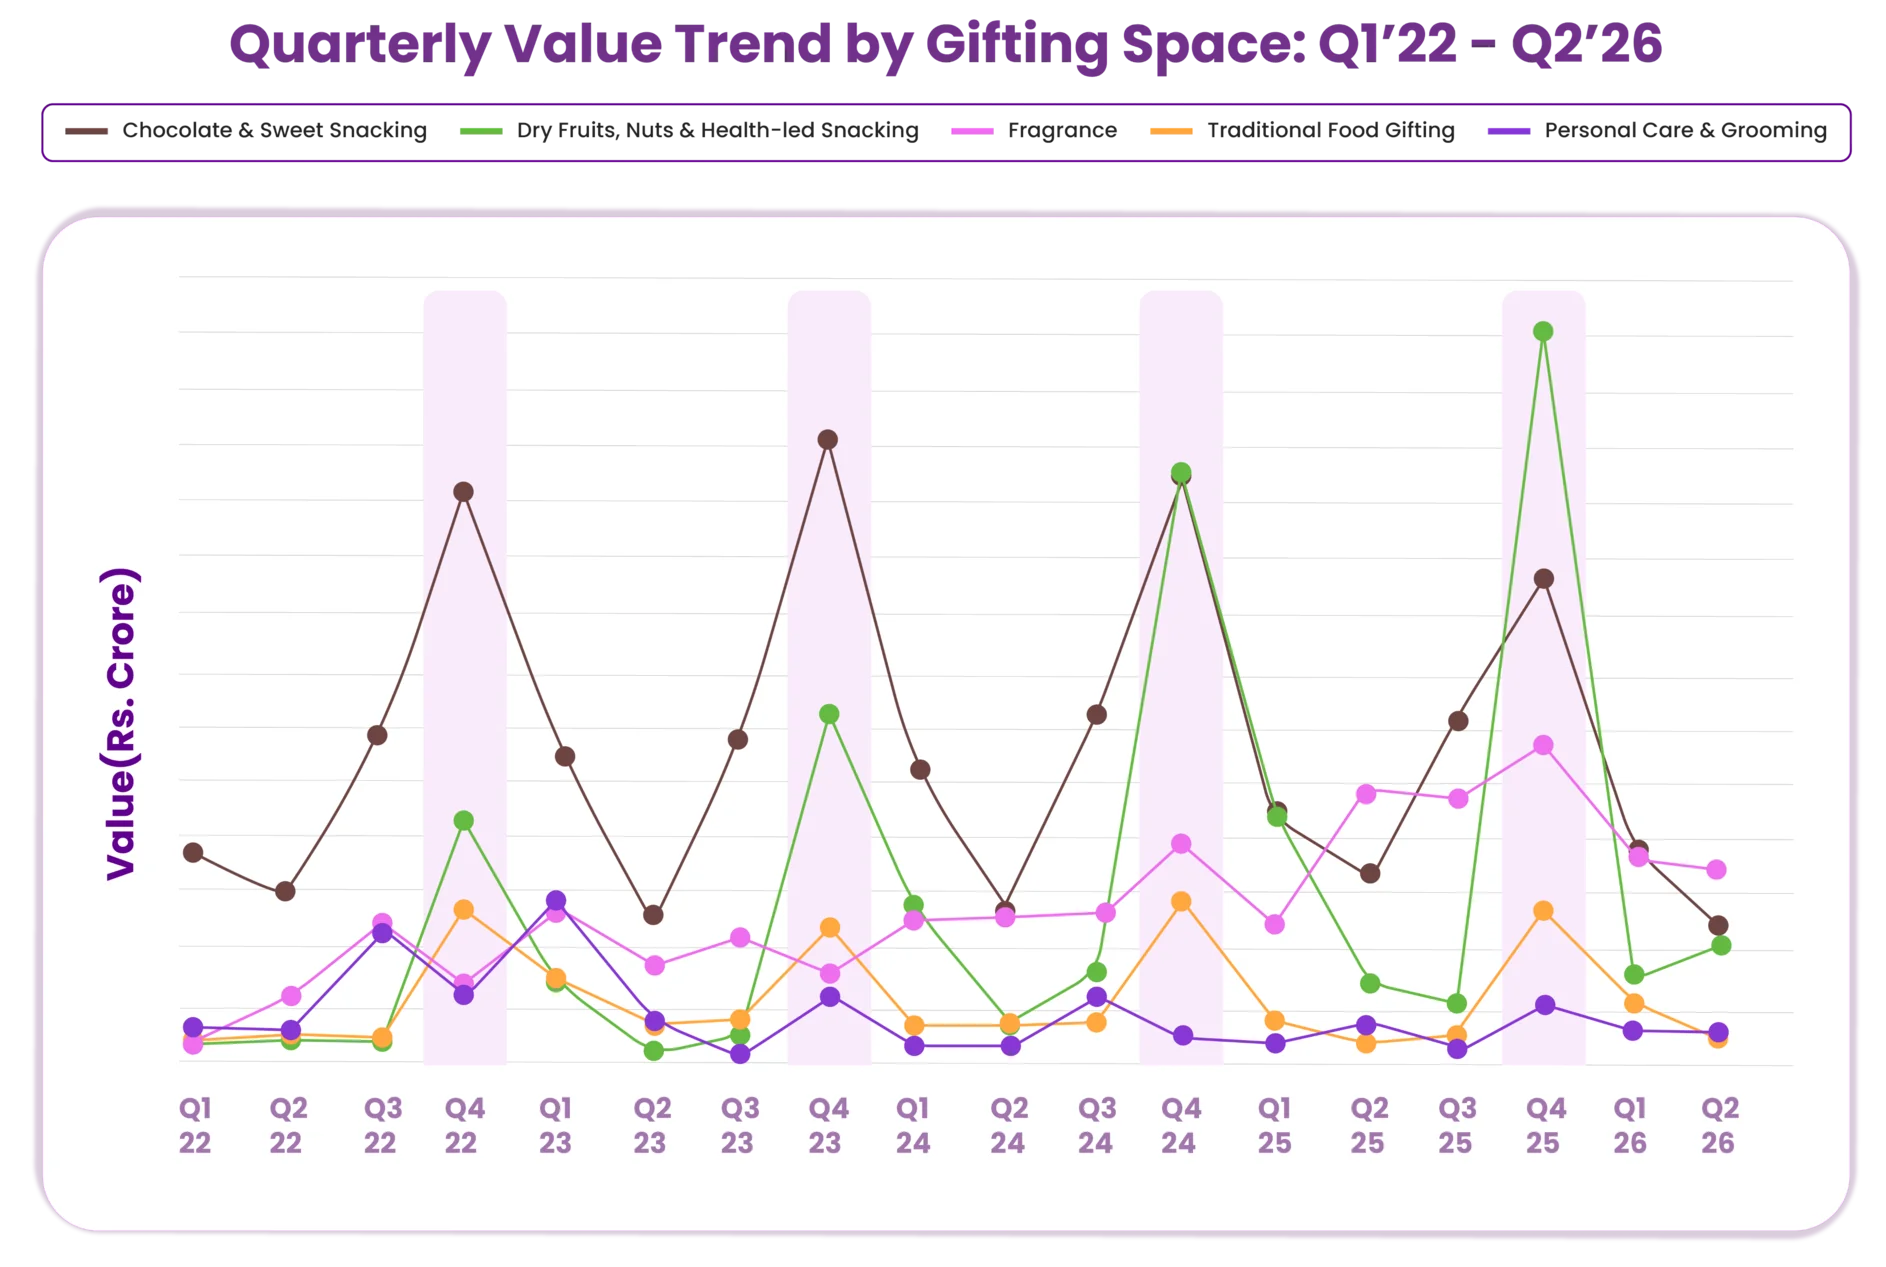
At the same time, Fragrance is building differently, with value spread more consistently across the year rather than depending on one seasonal spike. Together, this shows that the changing gifting basket is also reshaping when different gifting spaces matter most.
Quarterly Value Trend by Gifting Space: Q1’22 - Q2’26
Value (Rs. Crore)
- Chocolate & Sweet Snacking
- Dry Fruits, Nuts & Health-led Snacking
- Fragrance
- Traditional Food Gifting
- Personal Care & Grooming
New Households Are Shaping Gifting Spaces Differently
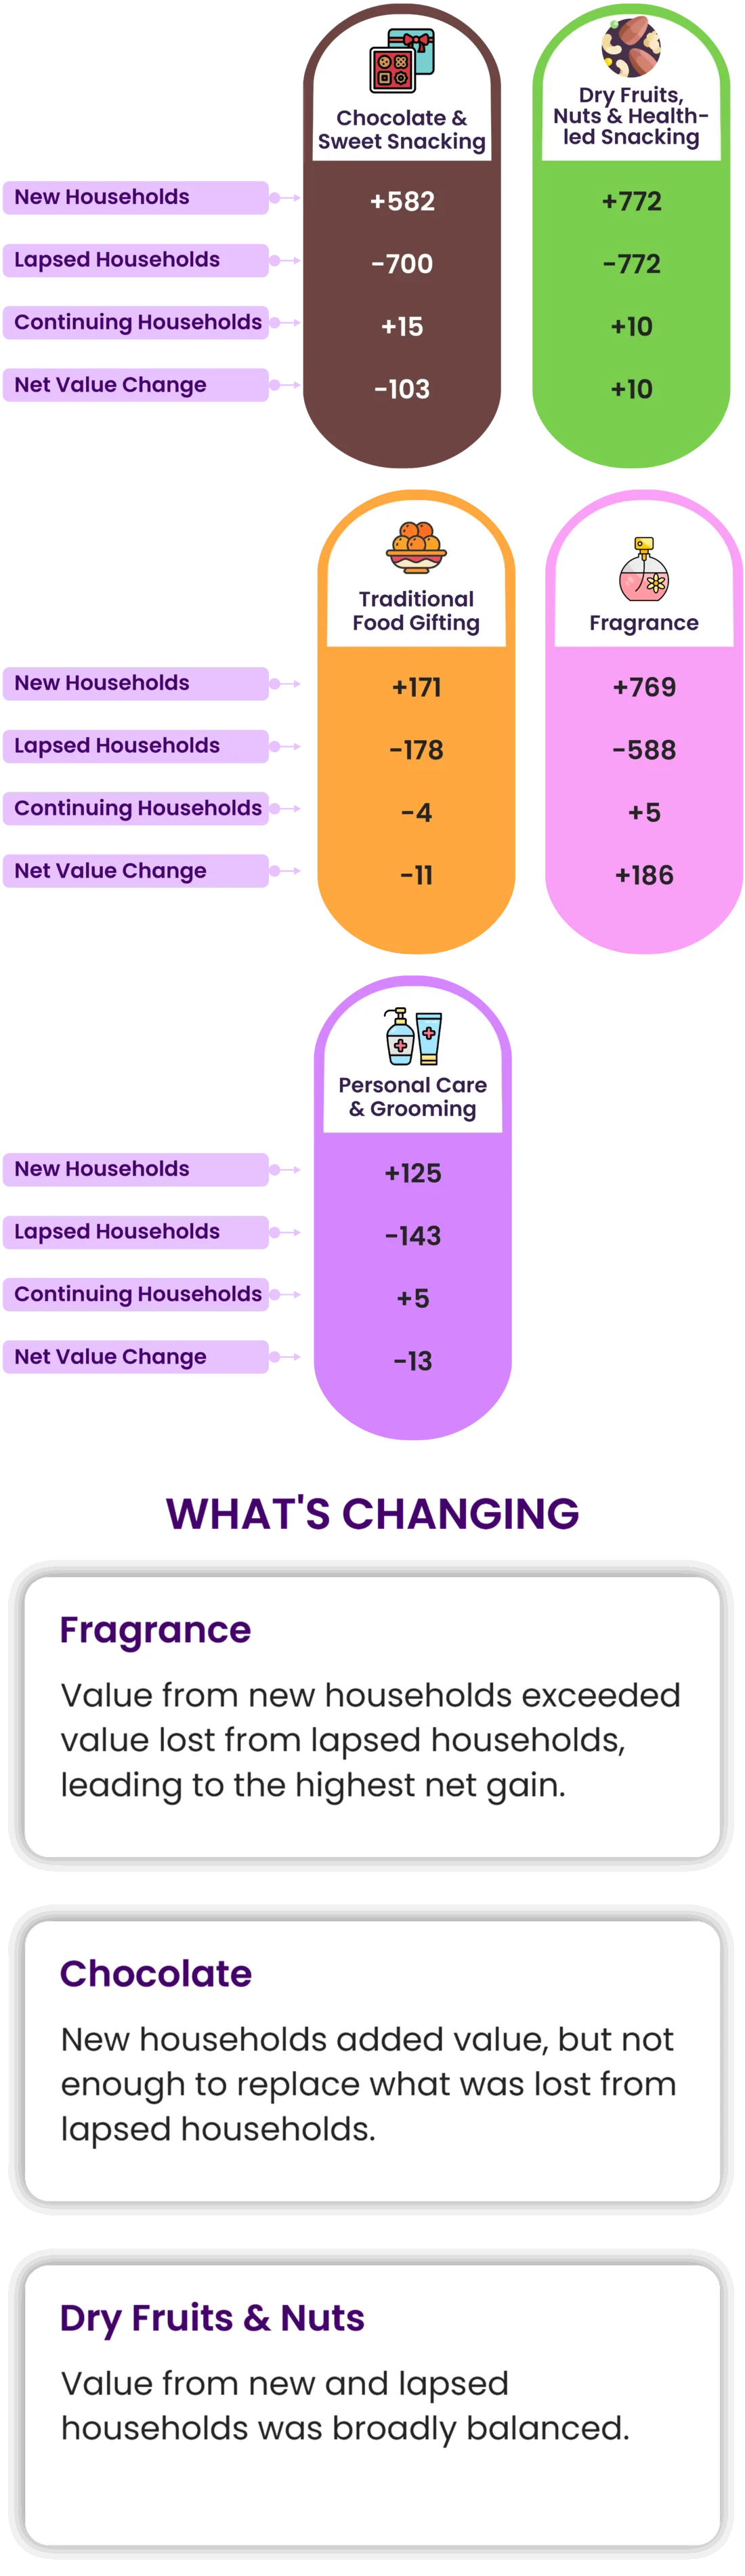
Changes in the five gifting spaces are coming from different household dynamics. In Fragrance, value from households newly entering the space outweighed the value lost from households that lapsed — the strongest net gain among the five spaces.
New Households Are Shaping Gifting Spaces Differently
MAT JUN25 - MAT JUN26 | Value contribution by household type (₹ million)
India-A, MAT JUN25 vs MAT JUN26 | Value contribution by household type (₹ million)
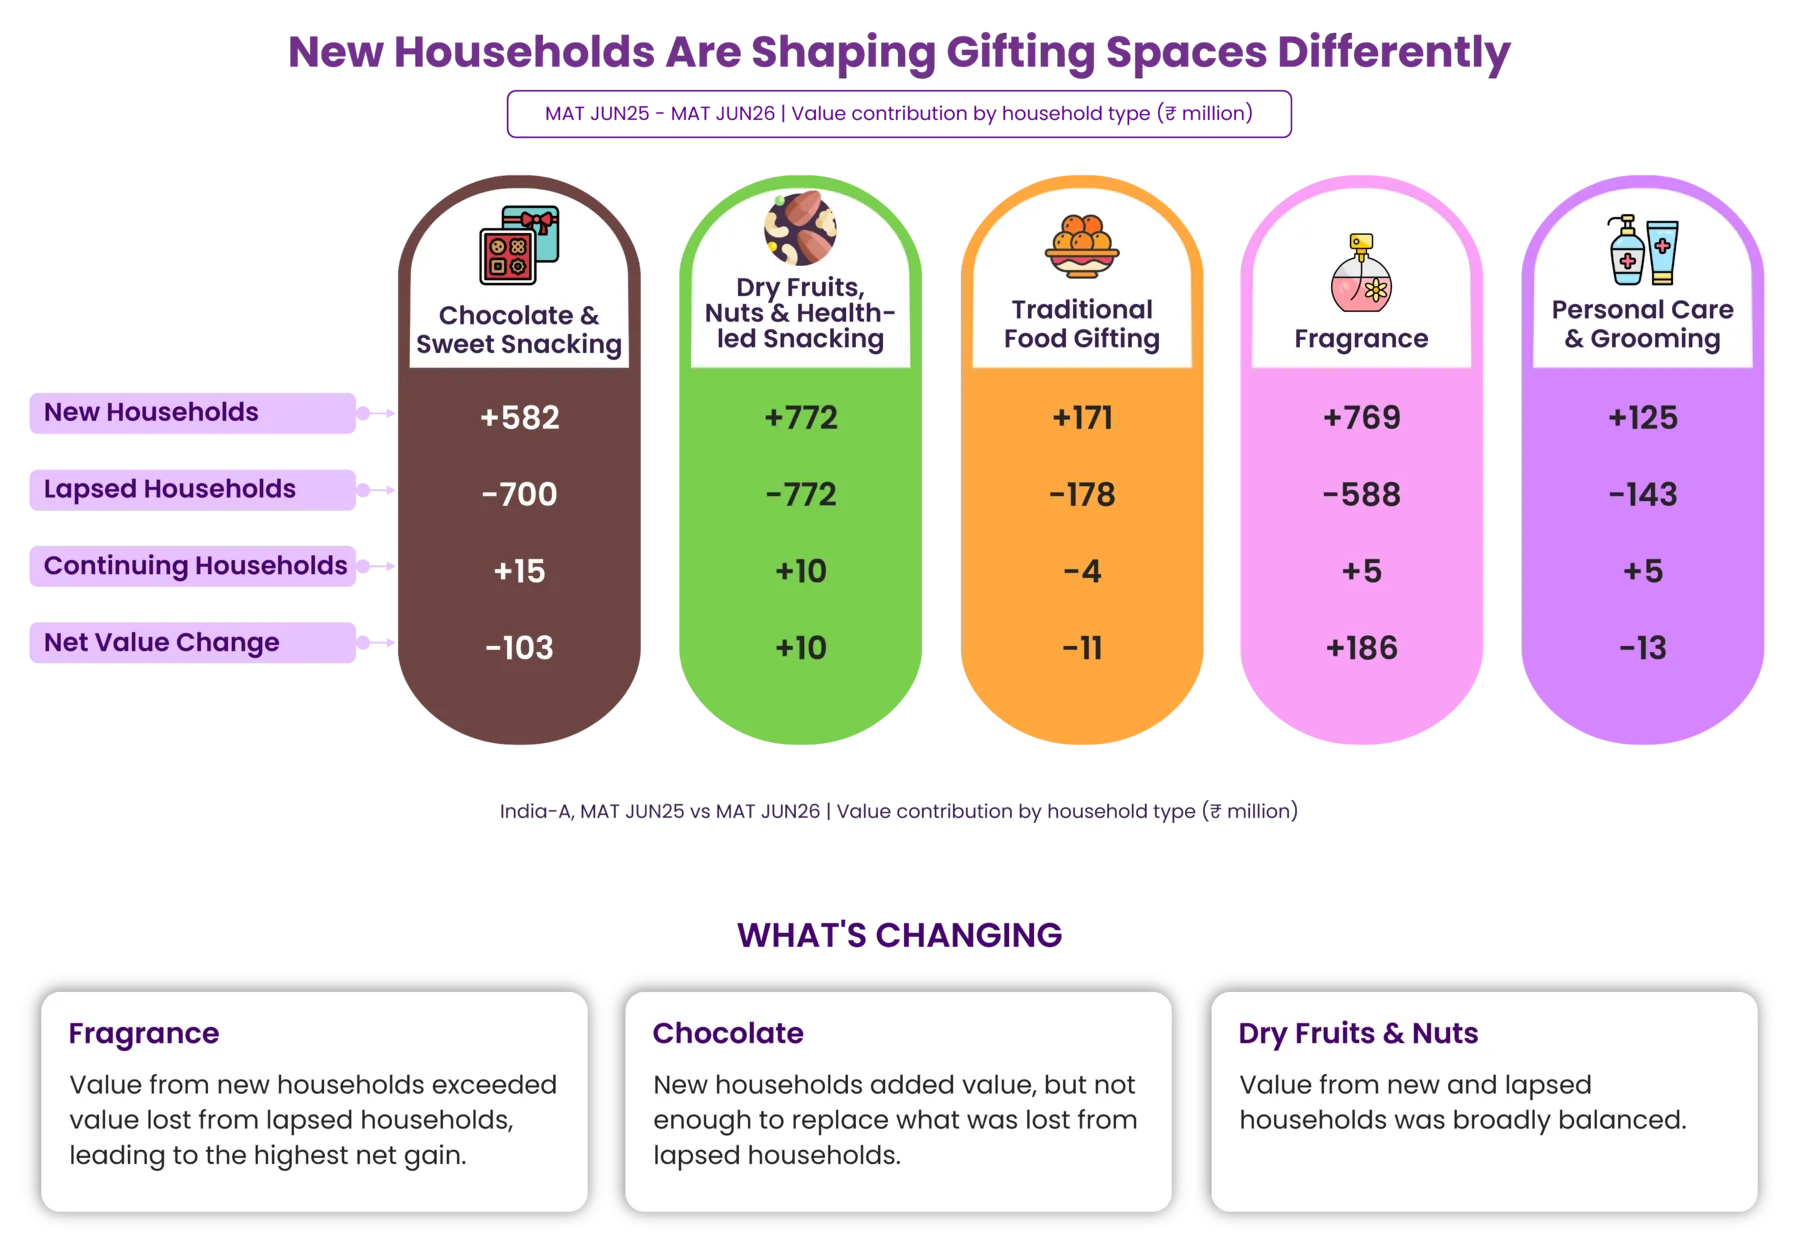
In Chocolate & Sweet Snacking, value from new households did not fully replace the value lost from lapsing households. Dry Fruits, Nuts & Health-led Snacking remained broadly balanced between the two.
New Households Are Shaping Gifting Spaces Differently
MAT JUN25 - MAT JUN26 | Value contribution by household type (₹ million)
India-A, MAT JUN25 vs MAT JUN26 | Value contribution by household type (₹ million)
Gifting Is Broadening Across Distinct Household Pools
A more diverse gifting market doesn’t necessarily mean a wider mix of gifting products is entering the same households. Among households with Chocolate, Eau de Parfum or Dry Fruits gifting products, the share with only Chocolate has fallen over the past two years, while the shares with only EDP or only Dry Fruits have grown.
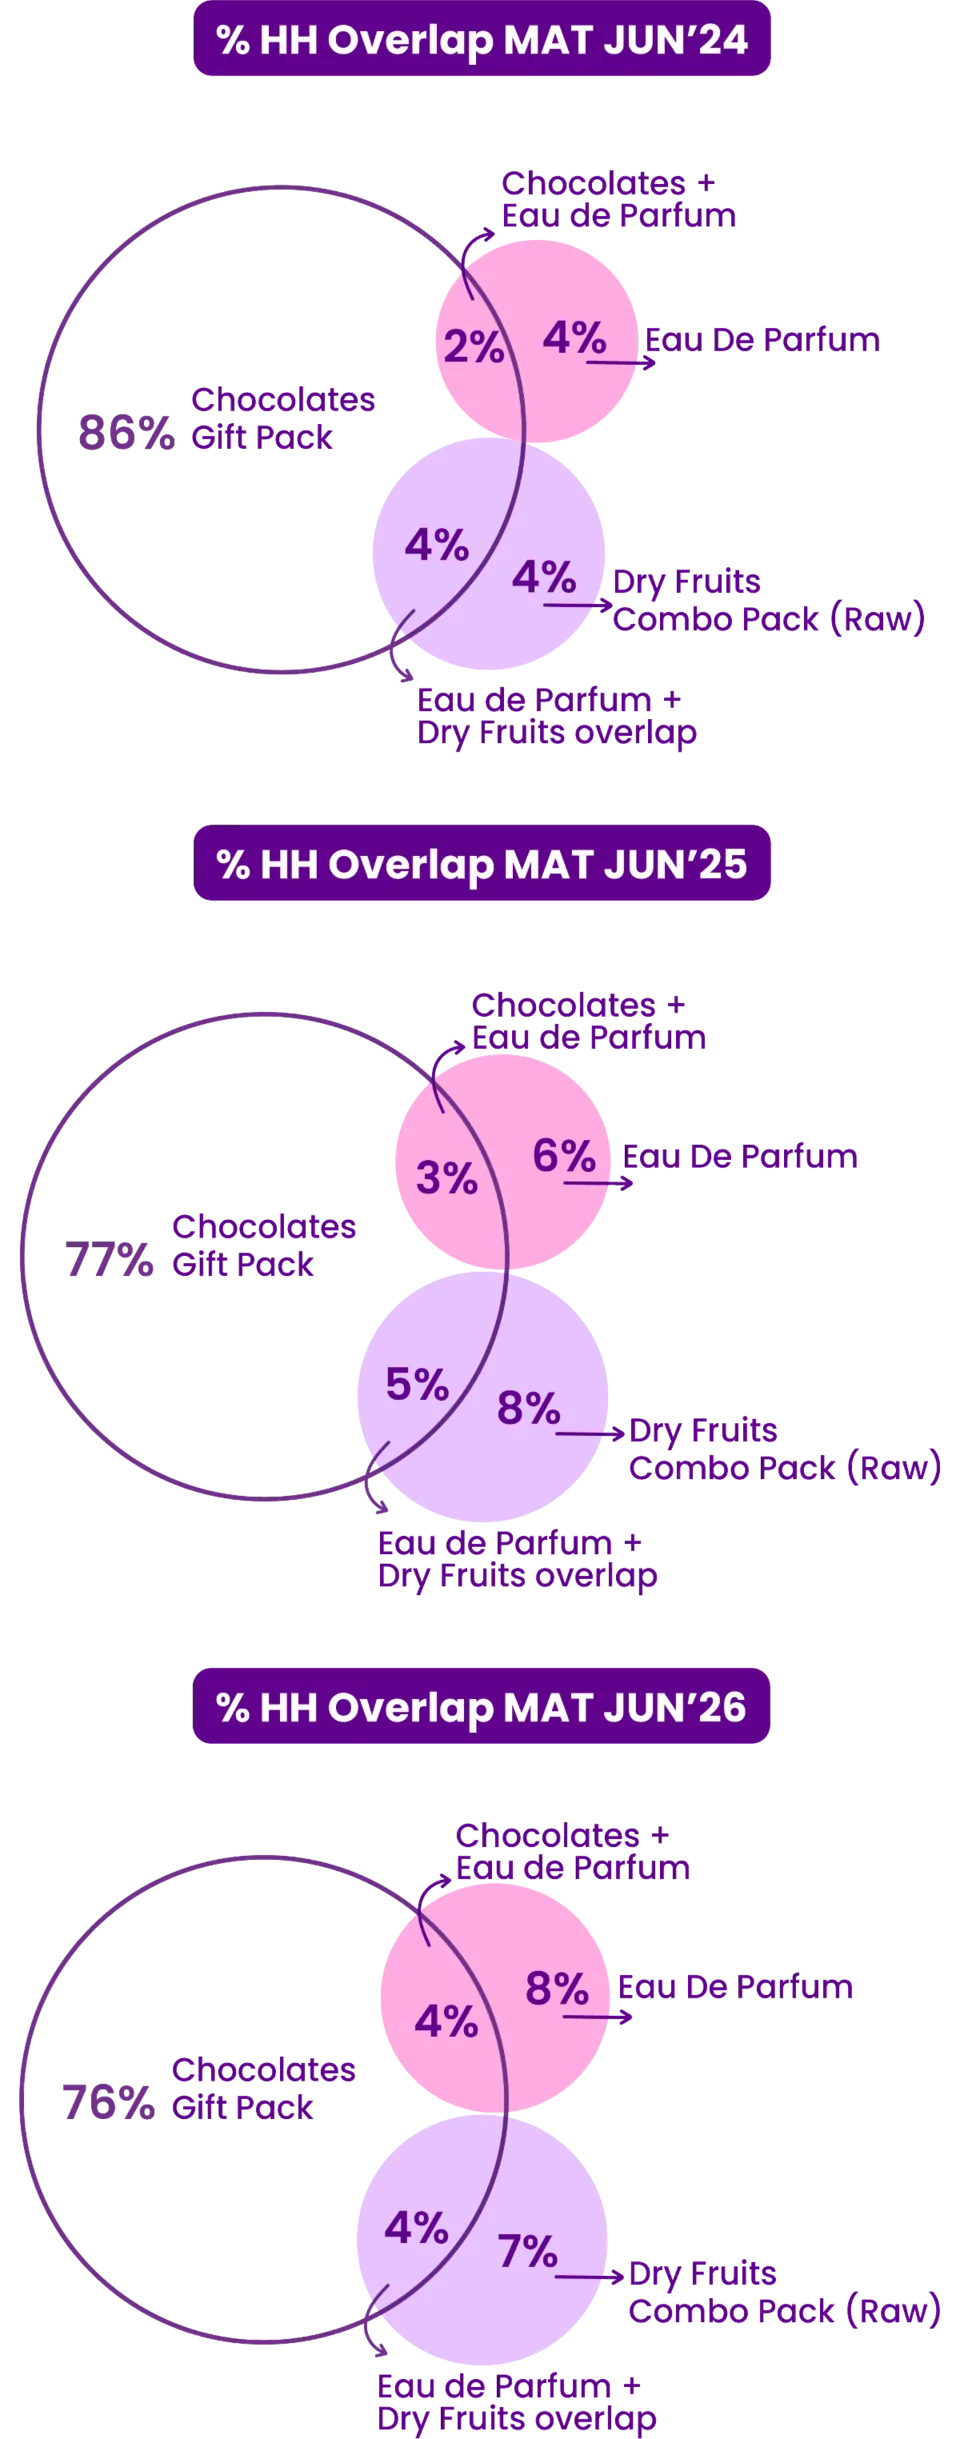
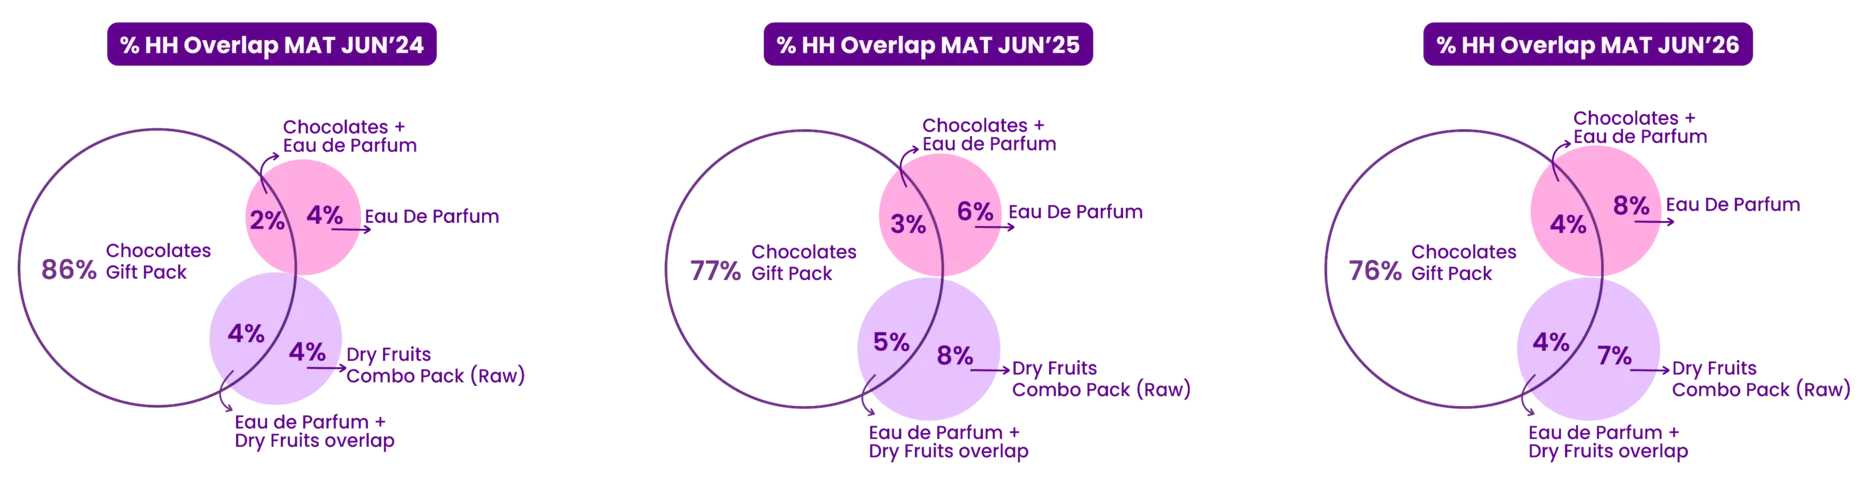
Overlap between the three remains limited, suggesting these formats largely reach different household pools.
Brand Competition Differs Across Gifting Spaces
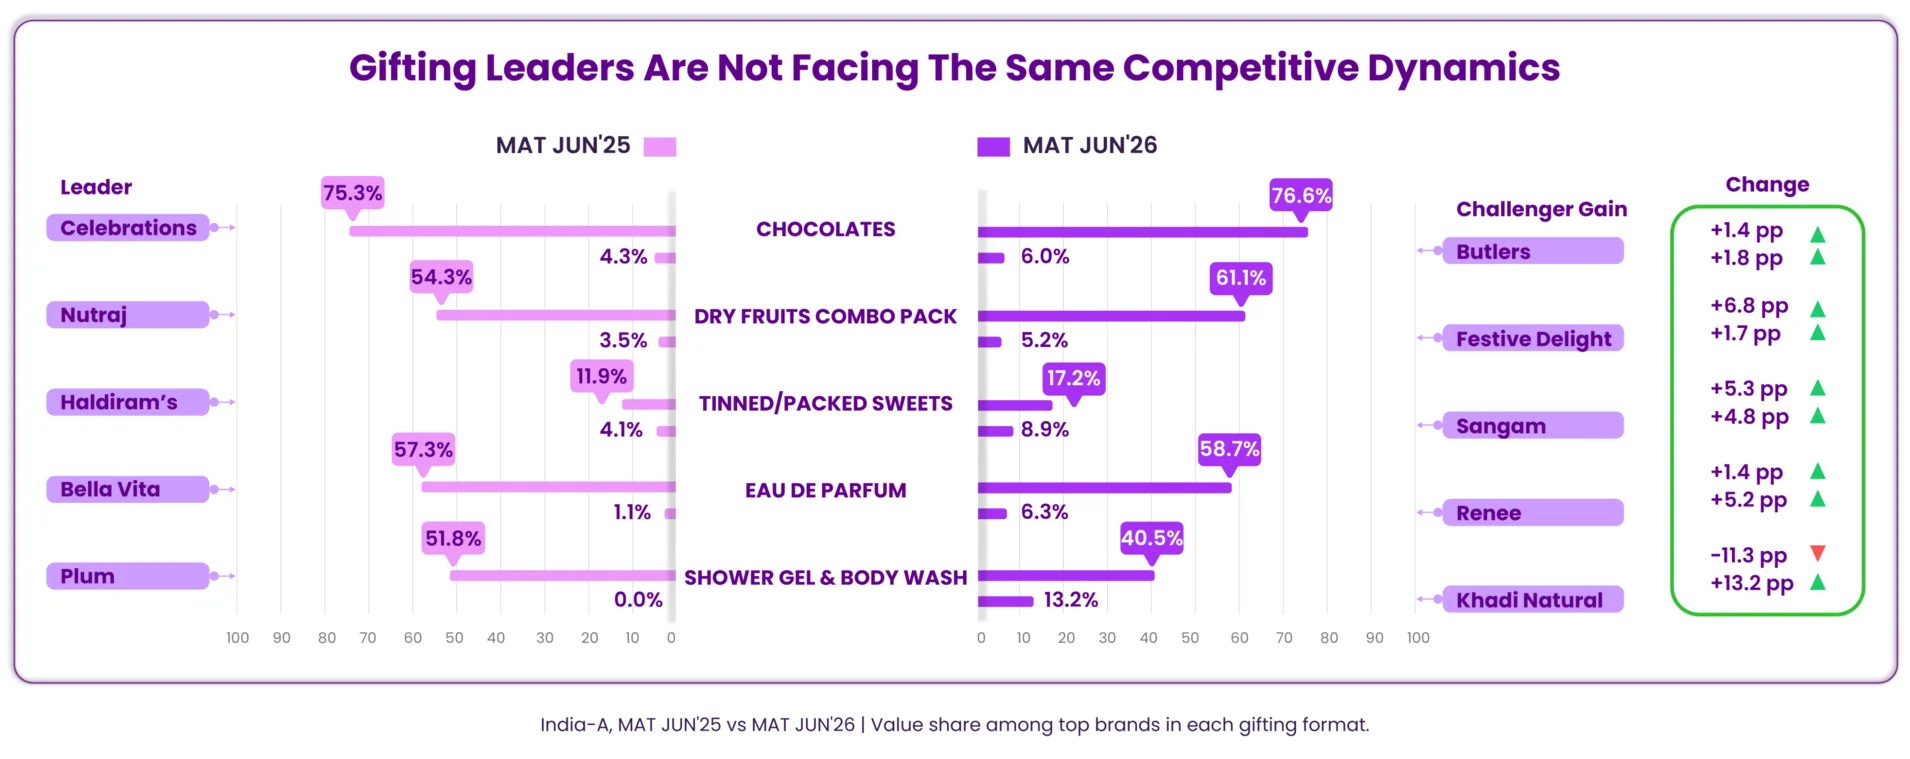
Some gifting spaces remain firmly led by one brand, while others are opening up. Celebrations and Nutraj strengthened their leadership, while Bella Vita remained the clear EDP leader even as Renee gained share. Shower Gel & Body Wash saw a bigger shift, with Plum losing share as Khadi Natural and other brands gained.
What This Means for Gifting
Gifting is becoming a broader FMCG occasion. Value is spreading out across the five gifting spaces, but there's no single reason behind the shift — each space is attracting a different group of households and facing a different competitive dynamic.
Learn More
Contents
More Binsights
Premiumisation Reshapes Branded Ghee In India-A
The India-A Consumption Story
Exclusive Read of India-A Homes: Walled Garden Consumers
Exclusive Read of India-A Homes: Walled Garden Consumers
40%
Of Urban Metro Population
48%
Of Urban Metro Consumption
22 Million
People In 6 Metros
5x
Consumption Of
Chocolates
5x
Spends On
Face Creams

22 Million
People In 6 Metros
5x
Consumption Of
Chocolates
5x
Spends On
Face Creams
1/3
Are Online Shoppers &
Use International Brands

45%
Consume Organic
Staples
2x
Spends On Hair Care

1/3
Are Online Shoppers &
Use International Brands
45%
Consume Organic
Staples
2x
Spends On Hair Care
22 Million
People In 6 Metros
5x
Consumption Of
Chocolates
5x
Spends On
Face Creams
1/3
Are Online Shoppers &
Use International Brands
45%
Consume Organic
Staples
2x
Spends On Hair Care
Get In Touch
Please enter details and we will get back to you